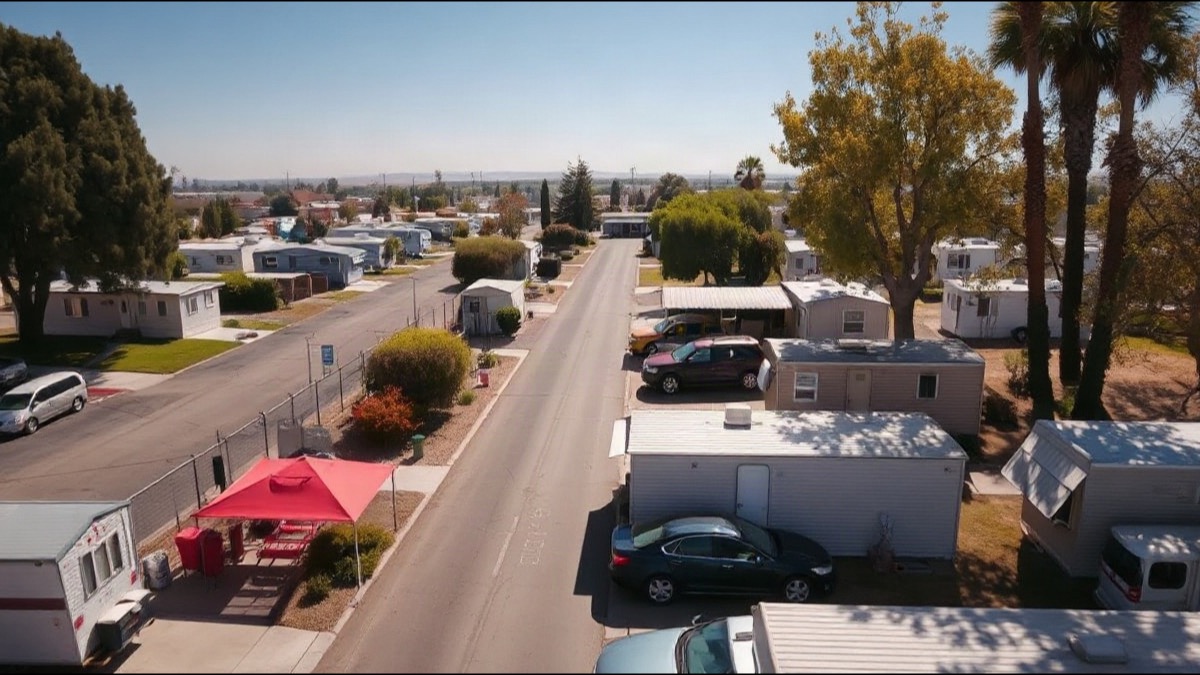
If you own or manage a mobile home park or manufactured housing community in Modesto, your insurance program looks nothing like a standard landlord policy — and the gap between what a generic property policy covers and what a park actually needs is exactly where costly claims fall through. This guide covers every coverage a Modesto mobile home park owner needs, what California law requires, and what a properly structured program costs.
Stanislaus County, where Modesto is the county seat, has a significant manufactured housing stock: according to the California Department of Housing and Community Development (HCD), manufactured and mobile homes represent a meaningful share of the region’s housing supply, particularly for working families and retirees seeking affordable homeownership. Insurance City’s parent operation serves 4,500+ active customers across three California offices and wrote 2,080 new policies in 2025. A Modesto mobile home park owner who carries the right insurance program can absorb a slip-and-fall on a common pathway, a utility failure that damages residents’ sites, or a lawsuit arising from park operations — without any of those events threatening the investment.
What insurance does a mobile home park owner need in Modesto?
Mobile home parks operate as commercial real estate businesses with a specific liability profile: the park owns the land and common infrastructure, while residents own (or rent) the homes on it. That split ownership creates exposures a standard landlord policy does not address. A complete insurance program for a Modesto mobile home park includes:
- Commercial general liability — covering bodily injury and property damage to residents, guests, and visitors arising from the park’s premises and operations
- Commercial property — covering the park’s common-area structures, utility hookup systems, roads, signage, clubhouse, laundry facilities, and any park-owned buildings
- Workers’ compensation — mandatory under California Labor Code §3700 from the first paid employee (managers, groundskeepers, maintenance staff, leasing agents)
- Commercial umbrella — extending liability limits above the GL base, which is critical for a premises business with dozens of residents and visitors on-site daily
- Commercial habitational property — required if the park owns any units it rents to residents, covering those structures separately from the land improvements
California’s Mobilehome Residency Law (Civil Code §798 et seq.) sets detailed obligations for park management — notice requirements, rent rules, eviction procedures, maintenance standards for common areas — but does not itself mandate a specific insurance minimum. In practice, lenders, park acquisition financing, and standard commercial risk management make a $1 million per occurrence GL policy the floor for most operating parks in the Central Valley.
The coverages every Modesto mobile home park needs
Commercial general liability
General liability is the foundation of a mobile home park insurance program. A standard $1 million per occurrence / $2 million aggregate GL policy covers third-party bodily injury and property damage arising from the park’s premises and operations — a resident who trips and falls on a poorly maintained common walkway, a guest injured in the park’s common area, a child injured at a park-operated playground, or damage to a resident’s home caused by a park utility failure. The “premises and operations” coverage trigger is critical for a land-lease community: the park is the operator of the space, and liability follows that role regardless of whether the injured party is a resident, a visitor, or a contractor working under park management direction.
For parks with a pool, clubhouse, or organized community activities, the GL policy needs to be written to address those specific premises exposures. Carriers who write mobile home park accounts understand the land-lease structure and build the policy accordingly — a generic commercial GL policy may contain exclusions that leave a park unprotected for its most common liability scenarios.
Workers’ compensation
Under California Labor Code §3700, workers’ compensation is mandatory from the moment a Modesto mobile home park hires its first paid employee — no minimum headcount, no grace period, and no exemption for park management operations. A resident manager, a groundskeeper who maintains the common areas and landscaping, a maintenance worker who handles unit repairs and utility systems, a leasing agent, or a part-time office staffer all trigger the coverage obligation the moment they are on payroll. A sole-owner park operator with no paid employees is generally exempt from the workers’ comp requirement for themselves, but that exemption ends the moment any paid worker is added.
The California Labor Commissioner can issue an immediate stop-work order and assess civil penalties against an uninsured employer under Labor Code §3700.5. For a mobile home park — a business whose residents depend on on-site management and maintenance — a stop-work order is not an abstract risk. Workers’ comp covers a manager’s back injury from moving appliances, a groundskeeper’s equipment-related injury, or a maintenance worker’s exposure to utility hazards. Each employee role carries its own class code, and an experienced agent builds the policy around your actual staffing structure.
Commercial property for park-owned structures and infrastructure
The park’s commercial property coverage insures the physical assets the park owns: the clubhouse and common-area buildings, the laundry facilities, the park office, signage, fencing, the utility distribution systems (water, sewer, electrical hookup infrastructure), internal roads and common pathways, and any park-owned amenities like a pool or recreation area. It does not cover the manufactured homes owned by residents — those are each resident’s separate insurance obligation.
For parks with aging infrastructure, the property coverage terms matter significantly. Replacement cost vs. actual cash value coverage is an important distinction for utility systems and community buildings that may have significant depreciation. Parks with common-area structures subject to California’s seismic risk also benefit from reviewing earthquake coverage options, which is typically a separate endorsement or standalone policy.
Commercial umbrella
A commercial umbrella policy extends the liability limits above what the underlying GL policy provides. For a mobile home park in Modesto where dozens of residents and their guests are on the premises daily, a $1 million per occurrence GL limit can be inadequate if a serious injury occurs — a permanent disability claim, a multi-party incident at the park pool, or a lawsuit alleging systematic habitability failures. A $1 million to $5 million commercial umbrella sits above the GL policy and responds when the underlying limit is exhausted. Most commercial lenders who finance mobile home parks require umbrella coverage as a loan condition, and the premium is typically the most cost-effective way to substantially increase total liability protection.
Mobile home park insurance coverage at a glance
| Coverage | What it covers | Required by |
|---|---|---|
| Commercial general liability | Bodily injury and property damage to residents, guests, and visitors on park premises | Lenders; standard operating practice; Civil Code 798 maintenance obligations |
| Commercial property | Clubhouse, laundry building, office, utility systems, internal roads, signage, amenities | Lenders; practical necessity for park operations |
| Workers’ compensation | Medical and lost wages for paid park employees injured on the job | California Labor Code Section 3700 from first paid employee |
| Commercial umbrella | Extends GL limits above the base policy; responds when GL limit is exhausted | Required by most commercial lenders; strongly recommended for multi-resident operations |
| Commercial habitational property | Park-owned units rented to residents (separate from land improvements) | Required when park owns rentable units |
What the park’s insurance does NOT cover
One of the most common questions from new mobile home park owners concerns coverage boundaries. The park’s commercial insurance program covers the park’s assets and liability exposure as the land operator. It does not cover:
- Residents’ manufactured homes — each homeowner is responsible for their own manufactured home insurance (dwelling, contents, and personal liability). Park managers often require proof of coverage as a lease condition under the rental agreement, but that resident policy is entirely separate from the park’s program.
- Residents’ personal property and personal liability — again, each resident’s own policy covers this.
- Flood damage — standard commercial property policies exclude flood; parks in FEMA flood zones along Modesto’s waterways should evaluate flood coverage through the National Flood Insurance Program or a surplus lines carrier.
The park-resident boundary matters at claim time: when a utility failure originating from the park’s distribution system damages a resident’s home, the park’s GL policy may respond if negligence is established. When damage arises from the resident’s own systems or a covered peril like fire, the resident’s own policy is the primary coverage. An experienced agent helps park owners understand exactly where that line sits before a claim occurs.
What mobile home park insurance costs in Modesto
Mobile home park insurance costs depend on the number of spaces, the size and age of park infrastructure, whether the park owns any units, the presence of amenities (pool, clubhouse), local claims experience, and the condition of utility systems. As working ranges for Modesto mobile home park accounts:
- Commercial general liability: $3,000–$8,000 per year for a small to mid-size park (50 to 150 spaces); larger parks with pools or extensive amenities run higher
- Commercial property: Depends on the replacement cost of park-owned structures and infrastructure; clubhouse-and-laundry-only parks run less than full-amenity communities
- Workers’ compensation: Depends on payroll and class codes for each role; a single resident manager on payroll costs significantly less than a full maintenance and leasing staff
- Commercial umbrella ($1M–$5M): $1,500–$4,000 per year over the underlying GL
These are working ranges, not quotes. Your actual premium depends on your park’s specific profile and the commercial carriers our agents access for mobile home park accounts. No broker fees on standard policies.
Serving Modesto mobile home park owners from Stockton
Mobile home park insurance requires an agent who understands the land-lease structure, the difference between the park’s liability exposure and the resident’s own coverage, and California’s Mobilehome Residency Law obligations that affect how the park manages its premises. A national call center will not ask about your utility infrastructure age, your on-site staffing model, or whether you carry a pool and clubhouse that create additional premises exposure.
We serve Modesto mobile home park and manufactured housing community owners by phone and by appointment from our Stockton office. Most commercial policies are quoted and bound without an office visit. Call (209) 670-1556 to speak with a licensed agent about your park’s program. Se habla español.
Frequently asked questions
What insurance does a mobile home park owner need in California?
A Modesto mobile home park owner needs commercial general liability, commercial property covering park-owned structures and infrastructure, workers’ compensation from the first paid employee under California Labor Code §3700, and a commercial umbrella to extend liability limits. Parks that own rentable units also need commercial habitational property coverage for those structures. California’s Mobilehome Residency Law (Civil Code §798 et seq.) governs park management obligations but does not set specific insurance minimums — lenders and standard commercial practice make $1 million per occurrence GL the floor.
Does a mobile home park in Modesto need workers’ compensation insurance?
Yes, from the moment the park hires its first paid employee. Under California Labor Code §3700, workers’ compensation is mandatory for any California employer with at least one employee. A resident manager, a groundskeeper, a maintenance worker, or a part-time leasing agent all trigger the obligation the moment they are on payroll. A sole-owner with no employees is generally exempt for themselves, but that exemption ends when any paid worker is added. The Labor Commissioner can issue a stop-work order and assess penalties under Labor Code §3700.5.
Does the park’s insurance cover residents’ homes?
No. The park’s commercial insurance program covers the land, the common-area structures, the utility systems, and the park’s liability as a premises operator. It does not cover the manufactured homes owned by residents. Each homeowner is responsible for their own manufactured home insurance. Park managers often require proof of residents’ home insurance as a lease condition, but that coverage and the park’s own program are entirely separate.
How much does mobile home park insurance cost in Modesto?
As working ranges for Modesto mobile home park accounts: commercial GL runs $3,000–$8,000 per year for a small to mid-size park; commercial property depends on replacement cost of park-owned structures; workers’ comp depends on payroll and class codes; a commercial umbrella adding $1M–$5M runs $1,500–$4,000 per year. Call our Stockton office at (209) 670-1556 for a quote based on your park’s profile.
Related reading: Mobile Home Park Insurance in Stockton, CA — Landlord & Rental Property Insurance in Stockton — Lee esta guía en español
Insurance City Agency — 956 W. Robinhood Drive, Stockton, CA 95207 — (209) 670-1556. Serving Modesto mobile home park owners from Stockton by phone — most commercial policies are quoted and bound without an office visit. CA License #6003045. Our licensed team brings more than 70 years of combined insurance experience.
Ready for a quote? Call or send the form
Call (209) 670-1556 Request a Quote
Serving Modesto from Stockton by phone · Se habla español · ITIN accepted. Insurance City Agency, LLC · CA License #6003045.